Private retirement planner
Humble Nest Egg
The retirement plan you own
Can you retire when you want, and how much can you safely spend? Answer five questions with round numbers and see your answer in under 5 minutes, tested against 155 years of real market history. No sign-up, no bank login, no subscription.

Why it's different
A serious plan, without the sign-up
Most finance apps want an account, a trial or your bank login before they show you anything. Humble Nest Egg has no door at all: open it, answer five questions, and see your plan.
No email, no password, no trial clock, no bank login. Round numbers are fine, and your answer comes in under 5 minutes.
2026 federal tax brackets, how Social Security is taxed, claiming from 62 to 70, required withdrawals at 73 or 75, and what changes for a surviving spouse.
Not just a single percentage. Your plan replayed through every start year since 1871, including 1929, 1966 and 2008, and 2,000 possible futures built from real market years.
Tap Why? on any answer and follow it from what you entered to the result. Check it, explain it to your partner, or take it to your advisor.
Your plan stays on your iPhone and in your own iCloud. No account, no bank logins, no ads, no analytics. Data Not Collected.
Free to use with one full plan. Unlock everything for $9.99, once: less than one month of a typical planning subscription. Family Sharing included.
The answer
Can you retire when you want?
A straight answer, not a guess
The question most people approaching retirement have is simple. The free calculators answer it with one number and no explanation; the serious tools want your bank logins or a subscription. This one gives you the answer, the test behind it, and nothing to sign up for.
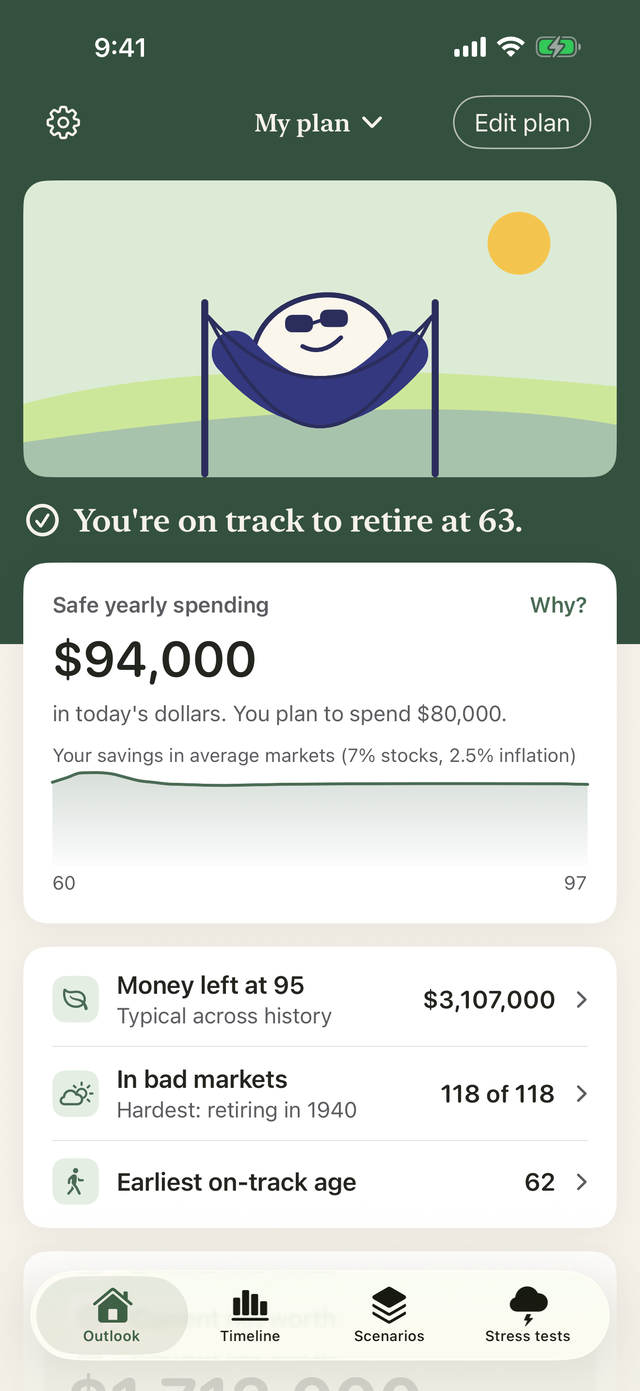
Safe yearly spending
The most you could spend each year and still make it through at least 90% of the start years in market history, solved for your plan rather than taken from a rule of thumb.
On track, close or a stretch
A plain verdict, the earliest age you could retire and stay on track, and how your plan did in the hardest stretch of history.
Built for reading
Large, clear numbers and calm colors, with full support for larger text sizes and light and dark mode.
Every year
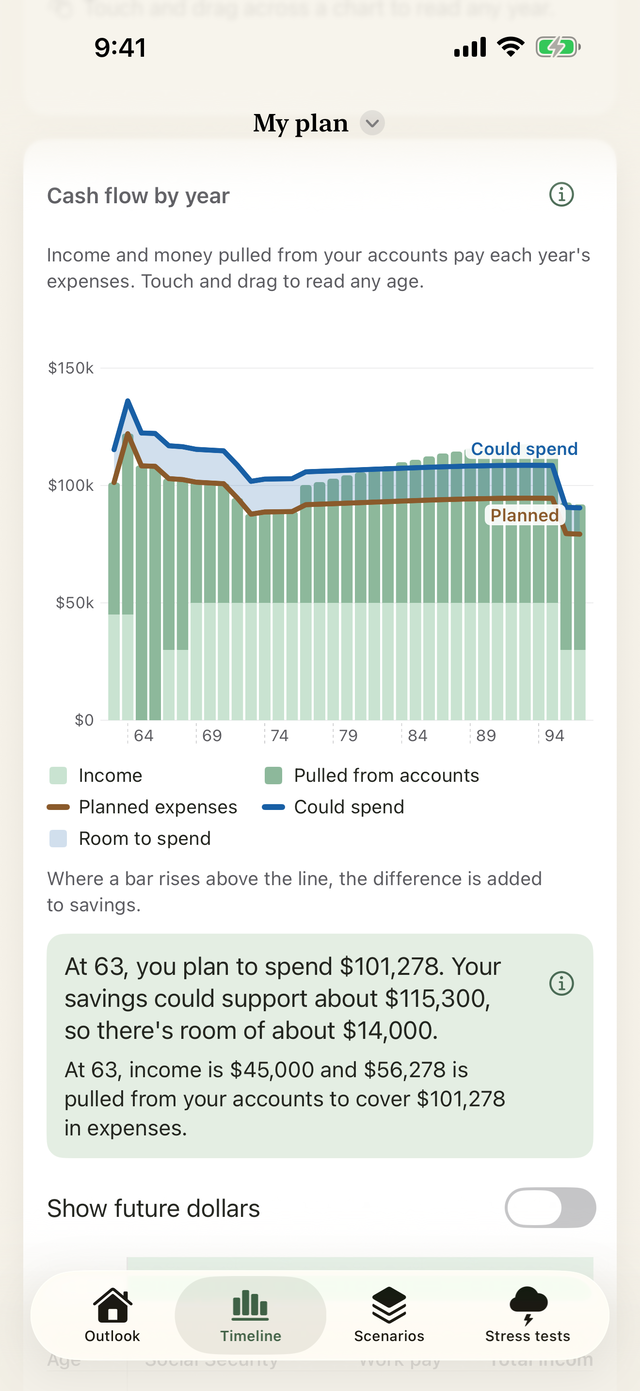
See what comes in, what goes out, and what you could spend
Every number is in today’s dollars unless you ask for future ones, so an amount thirty years away still means something.
Cash flow by year
Your income, what’s pulled from which account, your expenses and taxes, and anything added back to savings, year by year.
Room to spend
A second line shows what your savings could support beside what you plan to spend, so you can see the room, or the stretch.
Markets, your way
Switch between average markets, a typical stretch of history and a bad start, and see what changes. Today’s dollars or future dollars.
Shows its work
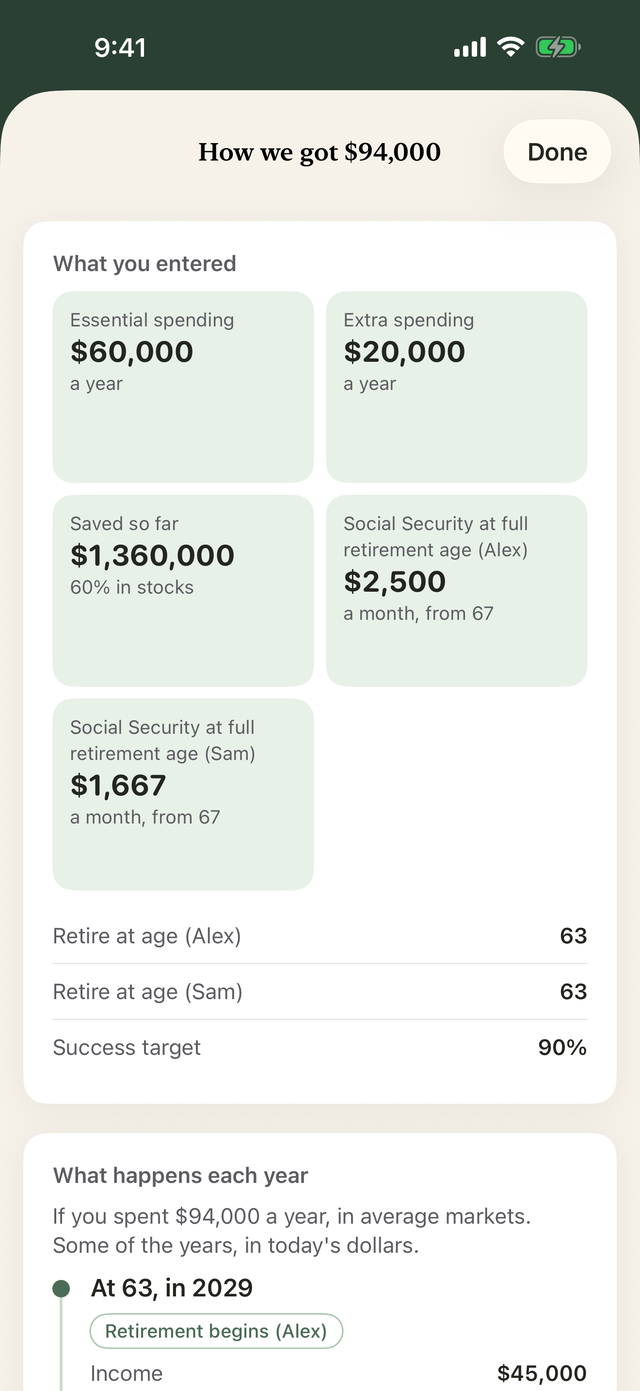
Every number shows its work
A PDF report and a spreadsheet of every year let you share the whole plan with your partner or your advisor.
What you entered
Your savings, spending, Social Security and ages, the inputs behind the answer.
What happens each year
Key years from your plan: income, what’s pulled from your accounts, taxes, expenses and savings.
Where every figure comes from
How it works, what it simplifies, and every tax, Social Security and market source, with links. Market history from Robert J. Shiller, used with permission.
What could go wrong?
Six stress tests, each with the smallest fix
Stress tests, scenarios, the 2,000 possible futures and the reports are part of the one-time unlock.
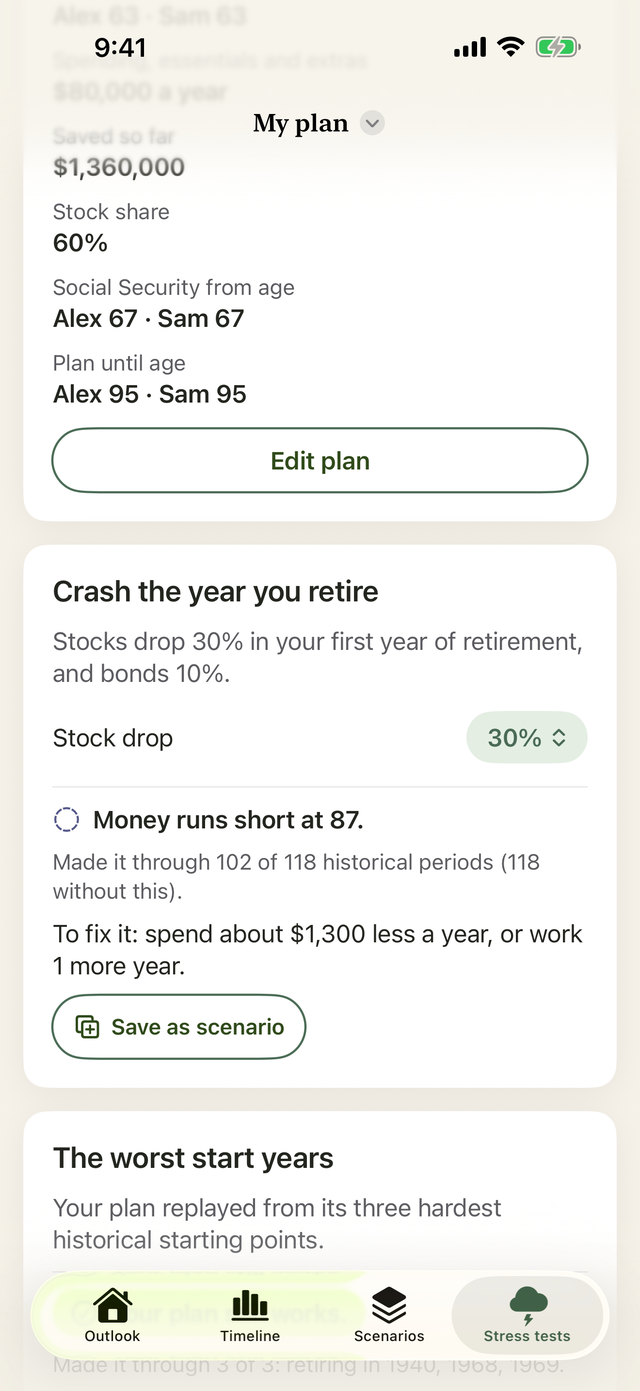
A crash the year you retire
What if stocks drop 30% in your first year? See whether your plan survives, and the smallest change that fixes it.
The worst start years
Your plan replayed from its three hardest historical starting points.
And four more
High inflation, living to 100, a long-term care bill, and work ending early. Each one with a one-tap “Save as scenario.”
What if?
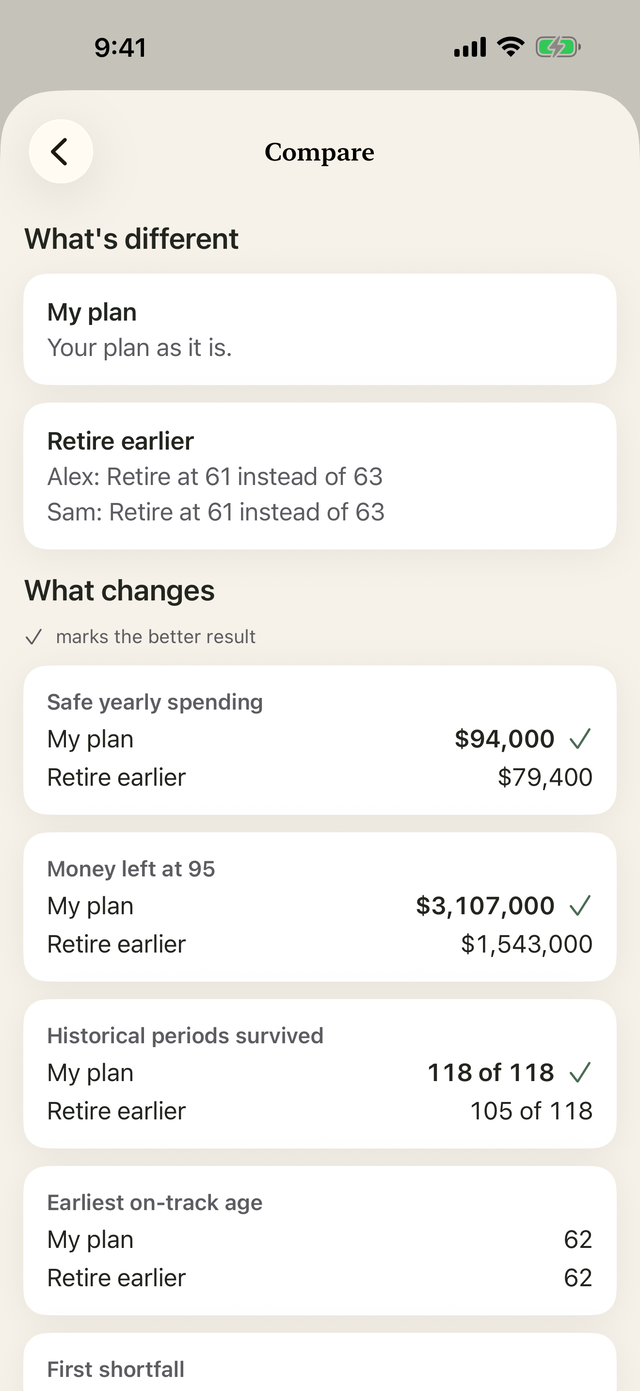
Retire at 62 or 65? See them side by side.
Scenarios
Retire earlier or later, claim Social Security at 70, spend less, downsize, pay off the mortgage, convert to Roth. Each one leaves your plan untouched.
Compare
Safe spending, money left, historical periods survived and lifetime taxes, side by side, with the better result marked.
Your net worth and FI number
Your savings, home and debts in one place, beside the 4% rule and your FI number, with where the rule comes from.
Private by design
Nothing to sign up for, nothing to collect
Humble Nest Egg is a planning tool, not financial, tax or legal advice. Results are estimates based on your inputs, 2026 tax rules and historical market data. The future can differ.
No account, no bank logins
You type in round numbers yourself. The app never asks for your logins and never connects to them.
Your iPhone and your iCloud
Your plan stays on your iPhone and syncs only through your own private iCloud. We can’t see it, so we have nothing to sell and nothing to lose.
Data Not Collected
No analytics, no ads, no network requests of our own. Lock the app with Face ID if you like.
A serious retirement plan. No bank logins. No subscription.
Free to use with one full plan. Unlock everything for $9.99, once. Family Sharing included.